Fixed rates, spot assets and partial liquidations: Nolus does not promise to eliminate the risks of leverage, but it is trying to prevent one bad market sequence from immediately turning into a disaster.
In DeFi, leverage promises greater exposure and potentially higher returns. Its other side is less appealing: variable financing costs, liquidations triggered by a wick lasting only a few seconds, and positions wiped out at the worst possible moment. Nolus has built its identity around this problem.
After covering its evolution between Cosmos and Solana in our previous article, let us change perspective. The network is ultimately only a means to an end. To understand Nolus, we need to look at the product: a form of spot margin designed to make leverage more predictable and liquidations less brutal.
From “DeFi Lease” to spot margin
Nolus was not created as yet another perpetuals platform.
The protocol originally described its product as DeFi Lease: enabling users to acquire more of an asset with limited initial capital, financed by a pool of lenders. The user provides a down payment, Nolus adds borrowed funds, and the combined amount is used to purchase the chosen asset.
The position therefore holds the actual spot asset rather than merely tracking its price. It remains non-custodial and is managed by the protocol’s contracts.
The leasing product later evolved into a spot margin engine capable of supporting long and short positions, stop-loss and take-profit orders, and other risk-management tools. Nolus describes this evolution as its transition into a fully fledged asset-backed margin engine.
What does the user actually do?
Imagine a user who believes in SOL’s potential but wants more exposure than their available capital would normally allow.
They connect Phantom or Solflare, select the asset and provide, for example, 1,000 USDC. With an additional 1,400 USDC borrowed through the protocol, they obtain 2,400 USDC of exposure to SOL. Both gains and losses are amplified: Nolus does not make leverage risk-free.
The user can, however, see the interest rate, debt level and liquidation threshold. They can repay debt, add capital, or close all or part of the position.
Nolus can offer exposure of up to 5x depending on the market, but this maximum is not uniform. The amount actually available depends on the asset, its liquidity and the relevant risk parameters.
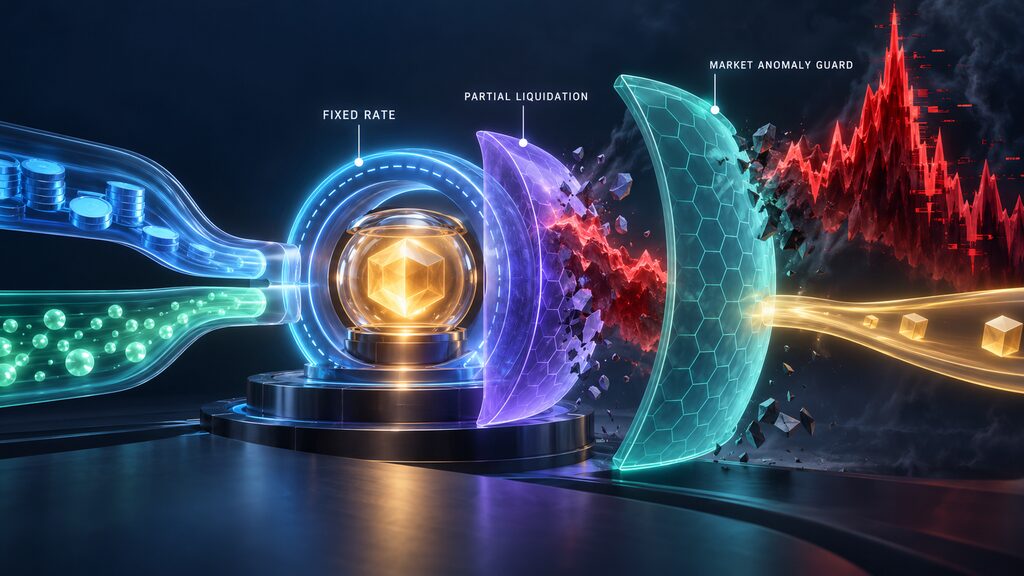
First difference: a cost known in advance
In perpetual markets, the funding rate changes according to the imbalance between long and short positions. A correctly positioned trade can therefore still be penalised by increasingly expensive funding.
Nolus uses a different model. The rate offered when a position is opened depends on how heavily the liquidity pool is being used: the greater the borrowing demand relative to the available funds, the more the cost of new positions may change.
But once a position has been opened, its rate remains fixed for its entire lifetime.
This does not guarantee a profit, but the user knows the cost from the outset — particularly valuable for a position held for several days or weeks. Predictability is one of the principles on which Nolus was built.
Second difference: liquidating only what is necessary
Nolus’s second defining feature is its system of partial liquidations.
When debt becomes too large, many products can close the entire exposure. The user then loses any chance of benefiting from a recovery, while their assets may be sold at a steep discount.
When a critical threshold is crossed on Nolus, the protocol first attempts to sell only the amount required to return the position to a healthier level. The remainder stays open.
Under the documented parameters, a position becomes eligible for liquidation when its debt reaches 90% of the position’s value. The partial sale aims to bring that ratio back towards 83%, although parameters may vary between markets.
If the price continues to fall, several partial liquidations can still eventually close the position. A single wick, however, does not necessarily mean the immediate loss of the entire exposure.
This is how Nolus’s claim of “no margin calls” should be understood: there is no discretionary demand for an immediate capital injection, but an automatic liquidation mechanism still applies when the risk becomes too high.
Third difference: avoiding a sale at any price
A liquidation may be justified by the health of a position while still being executed under extremely poor market conditions.
During a flash crash, the price available on a DEX can suddenly diverge from the broader market. An automatic sale at that precise moment may lock in an abnormal loss.
To limit this risk, Nolus developed the Market Anomaly Guard, or MAG.
Before execution, the system compares the expected proceeds of the sale with its oracle data. If the difference appears abnormal, the liquidation can be delayed and reassessed. An exponential moving average also helps filter out some very short-lived price movements.
A genuinely insolvent position must be reduced, but it should not be sacrificed because of a temporarily distorted price.
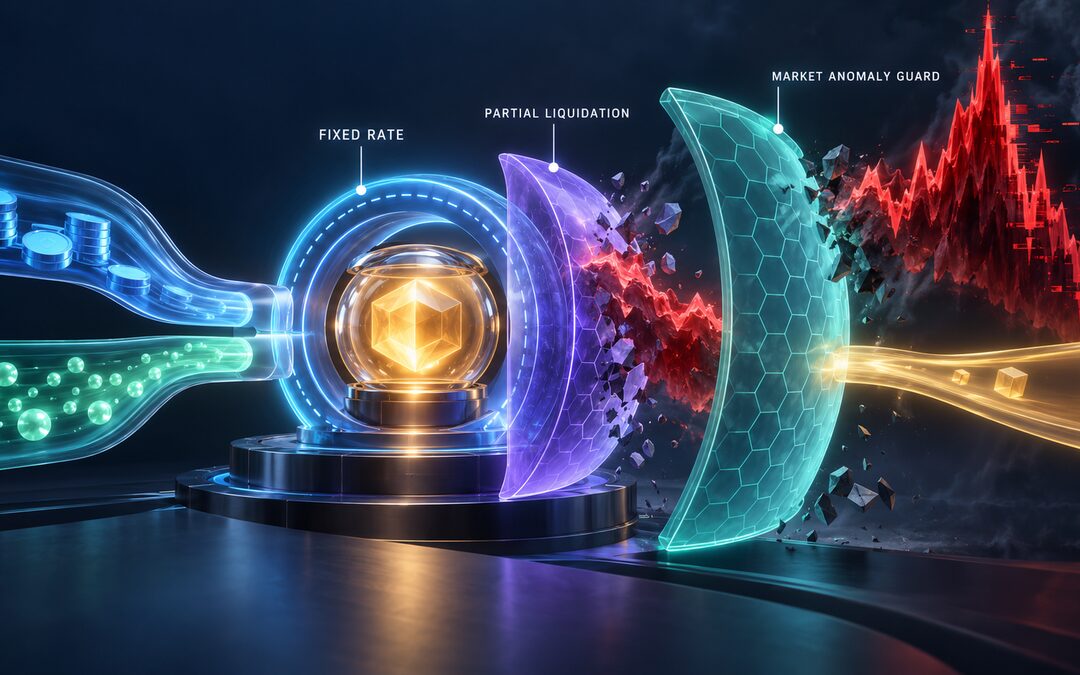
This combination — fixed rates, partial liquidations and MAG — is probably the clearest answer to the question: “What makes Nolus different?”
A first real-world stress test
This architecture has already faced a period of severe volatility.
During the violent deleveraging event of October 2025, Nolus says that around 81% of its portfolio remained intact. MAG reportedly protected almost 24% of active positions from liquidation at prices considered abnormal, with no bad debt or emergency intervention.
These figures come from Nolus itself, not from an independent study. They nevertheless provide a concrete example of how the system is intended to behave when markets become dislocated.
Why Solana matters to the product
Nolus’s arrival on Solana should not be presented as a simple change of blockchain.
For Nolus, it provides access to deeper liquidity, more users and greater DeFi activity. This could support larger positions, lower slippage and a broader range of assets.
At the time of our review, the official documentation listed four assets available for long positions in this market: SOL, cbBTC, HYPE and WETH. The offering therefore remains limited, and Nolus’s full architecture goes beyond what is currently accessible on Solana.
There is logic behind this caution: an asset needs sufficient liquidity for positions to be opened, closed and, when necessary, liquidated under acceptable conditions.
Solana is therefore not Nolus’s new identity. It is the environment in which the project intends to demonstrate that its product can scale.
Lenders and the role of NLS
Positions can only exist if lenders provide the required capital. They deposit stablecoins into liquidity pools and receive a share of the interest paid by users.
NLS incentives supplement this return. According to Nolus, part of the protocol’s revenue — interest margins, spreads and fees — is used to buy back NLS and replenish the incentives pool. NLS can also be staked to participate in network security and governance.
The model therefore attempts to connect product usage with the token. Without borrowing demand, however, there can be neither sustainable returns for lenders nor meaningful revenue to maintain this loop.
What Nolus still needs to prove
Its positioning is now clearer, but several challenges remain.
The asset catalogue is still small, and liquidity must grow without degrading rates or execution. The protocol also remains exposed to smart-contract, oracle and liquidity risks, as well as the specific risks associated with tokenised assets.
MAG and partial liquidations can limit some of the damage; they do not make leverage safe. A prolonged decline can still result in the complete loss of the capital committed.
Finally, Nolus remains a modest player compared with the largest lending and perpetual platforms. Its technology may be coherent without adoption following automatically. The real test will be whether it can attract borrowers, lenders and sufficient volume at the same time.
Conclusion: an identity stronger than a change of network
Nolus is not simply “a Cosmos project that moved to Solana.” That description explains its infrastructure but says almost nothing about why it exists.
The project is trying to build a third path between overcollateralised lending, which is cautious but capital-intensive, and perpetuals, which are efficient but can be unforgiving.
Its promise is not to remove risk. It is to make the cost of leverage more predictable, reduce weakened positions gradually, and prevent temporary market anomalies from triggering avoidable sales whenever possible.
That is what makes Nolus worth watching. Solana may provide the environment and liquidity it needs. The product must now prove that it can turn this technical differentiation into genuine adoption.
At Snow-Fall, this is what we will be monitoring: not just the price of NLS or the network being used, but real usage, pool depth and the model’s resilience when markets turn violent again.
This article is provided for informational purposes only and does not constitute financial advice. Leveraged products carry a significant risk of loss, including the total loss of the capital committed.
Main sources
- Nolus — How Does Nolus Work?
- Nolus — 2025: A Year in Review
- Nolus — Partial Liquidations Explained
- Nolus — October 2025 Crash
- Nolus Docs — Spot Margin
- Nolus — Changelog 2026.8
Nolus Wants to Make DeFi Leverage Less Brutal — Here Is How
Fixed rates, spot assets and partial liquidations: Nolus does not promise to eliminate the risks of leverage, but it is trying to prevent one bad market sequence from immediately turning into a disaster.
In DeFi, leverage promises greater exposure and potentially higher returns. Its other side is less appealing: variable financing costs, liquidations triggered by a wick lasting only a few seconds, and positions wiped out at the worst possible moment. Nolus has built its identity around this problem.
After covering its evolution between Cosmos and Solana in our previous article, let us change perspective. The network is ultimately only a means to an end. To understand Nolus, we need to look at the product: a form of spot margin designed to make leverage more predictable and liquidations less brutal.
From “DeFi Lease” to spot margin
Nolus was not created as yet another perpetuals platform.
The protocol originally described its product as DeFi Lease: enabling users to acquire more of an asset with limited initial capital, financed by a pool of lenders. The user provides a down payment, Nolus adds borrowed funds, and the combined amount is used to purchase the chosen asset.
The position therefore holds the actual spot asset rather than merely tracking its price. It remains non-custodial and is managed by the protocol’s contracts.
The leasing product later evolved into a spot margin engine capable of supporting long and short positions, stop-loss and take-profit orders, and other risk-management tools. Nolus describes this evolution as its transition into a fully fledged asset-backed margin engine.
What does the user actually do?
Imagine a user who believes in SOL’s potential but wants more exposure than their available capital would normally allow.
They connect Phantom or Solflare, select the asset and provide, for example, 1,000 USDC. With an additional 1,400 USDC borrowed through the protocol, they obtain 2,400 USDC of exposure to SOL. Both gains and losses are amplified: Nolus does not make leverage risk-free.
The user can, however, see the interest rate, debt level and liquidation threshold. They can repay debt, add capital, or close all or part of the position.
Nolus can offer exposure of up to 5x depending on the market, but this maximum is not uniform. The amount actually available depends on the asset, its liquidity and the relevant risk parameters.
First difference: a cost known in advance
In perpetual markets, the funding rate changes according to the imbalance between long and short positions. A correctly positioned trade can therefore still be penalised by increasingly expensive funding.
Nolus uses a different model. The rate offered when a position is opened depends on how heavily the liquidity pool is being used: the greater the borrowing demand relative to the available funds, the more the cost of new positions may change.
But once a position has been opened, its rate remains fixed for its entire lifetime.
This does not guarantee a profit, but the user knows the cost from the outset — particularly valuable for a position held for several days or weeks. Predictability is one of the principles on which Nolus was built.
Second difference: liquidating only what is necessary
Nolus’s second defining feature is its system of partial liquidations.
When debt becomes too large, many products can close the entire exposure. The user then loses any chance of benefiting from a recovery, while their assets may be sold at a steep discount.
When a critical threshold is crossed on Nolus, the protocol first attempts to sell only the amount required to return the position to a healthier level. The remainder stays open.
Under the documented parameters, a position becomes eligible for liquidation when its debt reaches 90% of the position’s value. The partial sale aims to bring that ratio back towards 83%, although parameters may vary between markets.
If the price continues to fall, several partial liquidations can still eventually close the position. A single wick, however, does not necessarily mean the immediate loss of the entire exposure.
This is how Nolus’s claim of “no margin calls” should be understood: there is no discretionary demand for an immediate capital injection, but an automatic liquidation mechanism still applies when the risk becomes too high.
Third difference: avoiding a sale at any price
A liquidation may be justified by the health of a position while still being executed under extremely poor market conditions.
During a flash crash, the price available on a DEX can suddenly diverge from the broader market. An automatic sale at that precise moment may lock in an abnormal loss.
To limit this risk, Nolus developed the Market Anomaly Guard, or MAG.
Before execution, the system compares the expected proceeds of the sale with its oracle data. If the difference appears abnormal, the liquidation can be delayed and reassessed. An exponential moving average also helps filter out some very short-lived price movements.
A genuinely insolvent position must be reduced, but it should not be sacrificed because of a temporarily distorted price.
This combination — fixed rates, partial liquidations and MAG — is probably the clearest answer to the question: “What makes Nolus different?”
A first real-world stress test
This architecture has already faced a period of severe volatility.
During the violent deleveraging event of October 2025, Nolus says that around 81% of its portfolio remained intact. MAG reportedly protected almost 24% of active positions from liquidation at prices considered abnormal, with no bad debt or emergency intervention.
These figures come from Nolus itself, not from an independent study. They nevertheless provide a concrete example of how the system is intended to behave when markets become dislocated.
Why Solana matters to the product
Nolus’s arrival on Solana should not be presented as a simple change of blockchain.
For Nolus, it provides access to deeper liquidity, more users and greater DeFi activity. This could support larger positions, lower slippage and a broader range of assets.
At the time of our review, the official documentation listed four assets available for long positions in this market: SOL, cbBTC, HYPE and WETH. The offering therefore remains limited, and Nolus’s full architecture goes beyond what is currently accessible on Solana.
There is logic behind this caution: an asset needs sufficient liquidity for positions to be opened, closed and, when necessary, liquidated under acceptable conditions.
Solana is therefore not Nolus’s new identity. It is the environment in which the project intends to demonstrate that its product can scale.
Lenders and the role of NLS
Positions can only exist if lenders provide the required capital. They deposit stablecoins into liquidity pools and receive a share of the interest paid by users.
NLS incentives supplement this return. According to Nolus, part of the protocol’s revenue — interest margins, spreads and fees — is used to buy back NLS and replenish the incentives pool. NLS can also be staked to participate in network security and governance.
The model therefore attempts to connect product usage with the token. Without borrowing demand, however, there can be neither sustainable returns for lenders nor meaningful revenue to maintain this loop.
What Nolus still needs to prove
Its positioning is now clearer, but several challenges remain.
The asset catalogue is still small, and liquidity must grow without degrading rates or execution. The protocol also remains exposed to smart-contract, oracle and liquidity risks, as well as the specific risks associated with tokenised assets.
MAG and partial liquidations can limit some of the damage; they do not make leverage safe. A prolonged decline can still result in the complete loss of the capital committed.
Finally, Nolus remains a modest player compared with the largest lending and perpetual platforms. Its technology may be coherent without adoption following automatically. The real test will be whether it can attract borrowers, lenders and sufficient volume at the same time.
Conclusion: an identity stronger than a change of network
Nolus is not simply “a Cosmos project that moved to Solana.” That description explains its infrastructure but says almost nothing about why it exists.
The project is trying to build a third path between overcollateralised lending, which is cautious but capital-intensive, and perpetuals, which are efficient but can be unforgiving.
Its promise is not to remove risk. It is to make the cost of leverage more predictable, reduce weakened positions gradually, and prevent temporary market anomalies from triggering avoidable sales whenever possible.
That is what makes Nolus worth watching. Solana may provide the environment and liquidity it needs. The product must now prove that it can turn this technical differentiation into genuine adoption.
At Snow-Fall, this is what we will be monitoring: not just the price of NLS or the network being used, but real usage, pool depth and the model’s resilience when markets turn violent again.
This article is provided for informational purposes only and does not constitute financial advice. Leveraged products carry a significant risk of loss, including the total loss of the capital committed.